Most of what's written about supercar finance is a product page. Tailored packages, competitive rates, your dream car. Very little of it explains what happens between "I want that car" and the keys being handed over.
We arrange supercar finance every day, on everything from a Porsche 911 to a LaFerrari, so this is the version we'd give a client who asked us to talk them through it properly. No rates, because those depend on you and the car. Just how a deal gets built, why most supercar agreements look the way they do, and where the decisions sit.
Why Supercar Finance Isn't Ordinary Car Finance
Three things are different, and they change everything about how a deal is put together.
The amounts. Supercar finance usually runs to six figures, so the structure of the agreement matters more than the headline rate. A small change to the deposit or the Final Payment (Balloon) moves the monthly payment by hundreds of pounds.
The cars. They're built in limited numbers, often bought used, sometimes fifteen or twenty years old, and their values move in ways a mainstream lender's model was never designed for. A high-street lender's rules on age and mileage are written for a three-year-old hatchback. They don't fit a 2005 Carrera GT.
The buyers. Company directors, business owners, people whose income comes through dividends, assets or more than one company. Affordability is real, it just doesn't sit neatly on a payslip.
Supercar finance is built around the car and the person. Ordinary car finance is built around a formula.
How a Supercar Finance Deal Is Built
Porsche 911 GT3 RS: deposit, term, monthly payment, Final Payment (Balloon)
Every agreement has four moving parts: the deposit, the term, the monthly payment and the Final Payment (Balloon). Move one and the others move with it.
A larger deposit lowers the monthly payment and the amount borrowed. A longer term lowers the monthly payment but adds to the total cost. A larger Final Payment (Balloon) lowers the monthly payment further, but it has to be dealt with at the end of the agreement: paid, refinanced, or cleared by selling the car.
That last point is the one we start with. Before we talk about numbers we ask two questions: how long do you intend to keep the car, and what do you want to happen at the end? A client who changes cars every eighteen months needs a different structure from one who plans to keep an F12 for a decade. The right deal is the one that matches the plan, not the one with the lowest monthly figure on the day.
At the end of the term there are three exits. Settle the balance and own the car outright. Refinance the Final Payment (Balloon) into a new agreement and keep the car. Or sell the car, clear the balance and move on to the next one. Most of our clients know which of those they want before they sign, and the deal is built backwards from it.
Supercar Hire Purchase With a Final Payment (Balloon)
Ferrari 488 Pista: most of our supercar finance is hire purchase with a Final Payment (Balloon)
Most of the supercar finance we arrange is hire purchase with a Final Payment (Balloon). It's the structure that suits how people actually own these cars.
It works like this. You pay a deposit, then a fixed monthly payment over an agreed term, with a larger Final Payment (Balloon) at the end. That balloon is set with reference to what the car is expected to be worth when the agreement finishes, which is what keeps the monthly payment manageable on a car worth several hundred thousand pounds. Once the final payment is made, the car is yours.
Two things distinguish it from PCP. There's no guaranteed future value and no option to simply hand the car back, which is why the balloon is set carefully and why it suits people who intend to own the car rather than lease it. And there are no mileage restrictions written into the agreement in the way a PCP has, though the balloon is calculated on an expected mileage, so a car driven far harder than planned will be worth less against it.
It's the structure to understand first, because almost everything else is a variation on it. Our hire purchase page goes through the mechanics in more detail.
Supercar Finance Compared: HP, PCP, Lease Purchase and Refinancing
McLaren 600LT Spider: HP, PCP, Lease Purchase or refinancing depends on the plan, not the car
Personal Contract Purchase gives you a guaranteed future value and the option to hand the car back at the end. That certainty is useful, but fewer funders offer it on high-value cars, it carries mileage limits, and the guaranteed value tends to be set conservatively. It suits someone who wants a fixed exit and expects to change the car at the end of the term.
Lease Purchase has a similar shape to hire purchase with a Final Payment (Balloon), with ownership passing at the end, but it's structured differently for accounting purposes and is often the better fit for business buyers. Which of the two suits you is a conversation about how the car will be owned and paid for, not about the car itself.
Equity release is finance raised against a car you already own outright, releasing capital while you keep the car. It's used for everything from funding a second purchase to freeing up cash in a business.
Refinancing replaces an existing agreement, most often to deal with a Final Payment (Balloon) that's coming due. If you want to keep the car when the balloon lands, refinancing it into a new agreement is usually the answer, and it's worth starting that conversation three or four months before the date.
What Lenders Look At With Prestige Car Finance
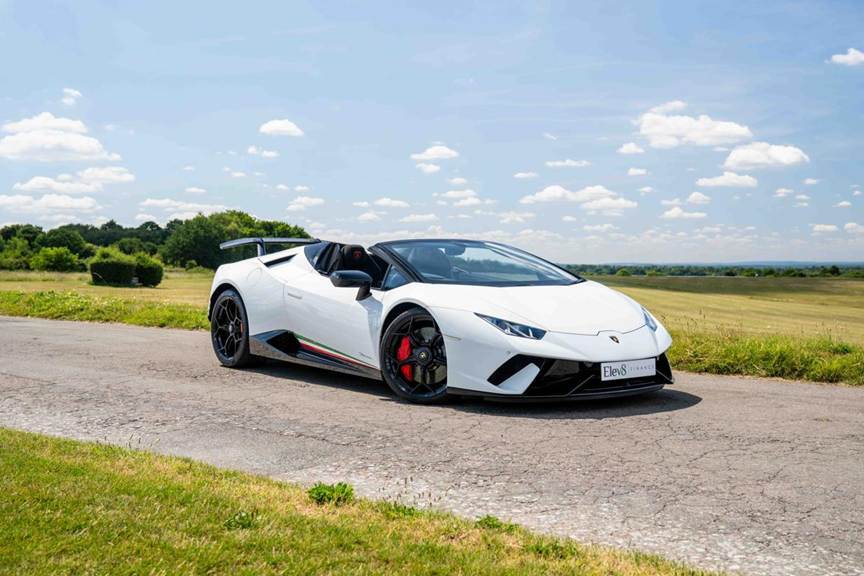
Lamborghini Huracán Performante Spyder: the car, the person and the structure
Three things: the car, the person and the structure.
The car first. Age, mileage, provenance and evidence of value. A specialist funder understands why a twenty-year-old Ferrari with 8,000 miles is a safer asset than a two-year-old saloon with 40,000. A mainstream one has a box that says "over ten years old" and stops there. That difference decides which funders can even look at the deal.
Then the person. For a company director or someone self-employed, affordability is shown through accounts, dividends and assets rather than three months of payslips. Specialist funders are used to reading that picture. It doesn't make the deal harder, it just means the application needs to be presented properly.
Finally the structure. Deposit, term and Final Payment (Balloon) in sensible proportion to the car. A deal that's stretched too far on any one of them is the deal that gets declined, or approved at a worse rate.
This is why a specialist lending panel matters. Different funders like different cars, different ages, different structures and different client profiles. Getting the right deal is mostly a matter of putting the right case in front of the right funder.
Where a Broker Changes the Outcome
Aston Martin Vantage: the finance is never the reason a client loses a car
A broker's job is to know which funder will say yes to this car, this person and this structure, and to get there quickly. Going direct to one lender means one set of rules. A panel means the deal is matched to the funder rather than squeezed into a single template.
Speed matters more than people expect. Good cars sell fast. When a dealer has three buyers for the same car, the one with finance agreed by the afternoon usually wins, and the buyer still waiting on a call back from a bank doesn't. We work with dealers across the country and a large part of what we do is making sure the finance is never the reason a client loses a car.
Then there's the structure conversation itself. Most people know what monthly payment they're comfortable with. Fewer have thought about the exit, the balloon, or what happens if they want to change cars in two years.
That's the conversation that saves money, and it's the one a product page can't have with you.
We've written more on the difference between a specialist broker and going direct.


