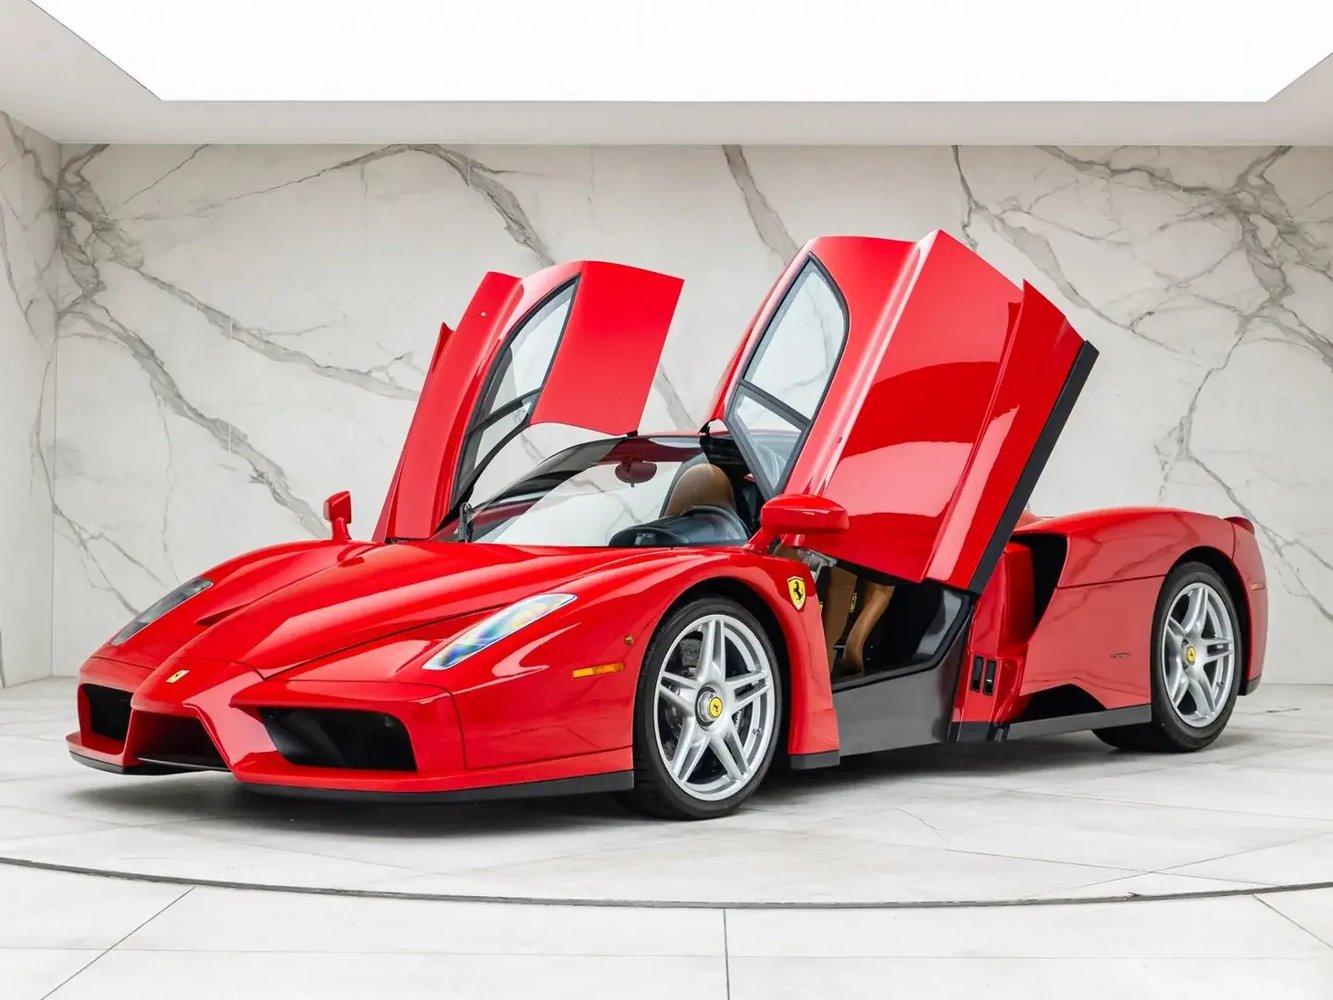
Ferrari's six halo cars, the 288 GTO, F40, F50, Enzo, LaFerrari and F80, were each the most advanced road car Maranello could build in their day. Search for a Ferrari F40 price, a Ferrari Enzo price or a LaFerrari price and you'll quickly see they sit in a world of their own. So it's no surprise that we're asked, more often than you might expect, how you actually finance a car like this. The answer isn't about finding the lowest rate. It's about building the right structure around a very particular car.
Can You Get Finance on a Ferrari Halo Car?
In many cases, yes. We arrange finance on high-value Ferraris regularly, and a halo car follows the same principles as any other: a funder needs to understand the car, its value and the person buying it. What changes is how few funders are comfortable at this level. Some halo cars are more than 30 years old, every one is worth a serious sum, and a mainstream lender looking at one through a standard used-car model is unlikely to get it right. That is where a specialist panel, and a broker who knows which funder suits which car, makes the difference. Every case is different, so the first conversation is always about the specific car.
Ferrari F40 and F50 Finance: Funding an Older Halo Car
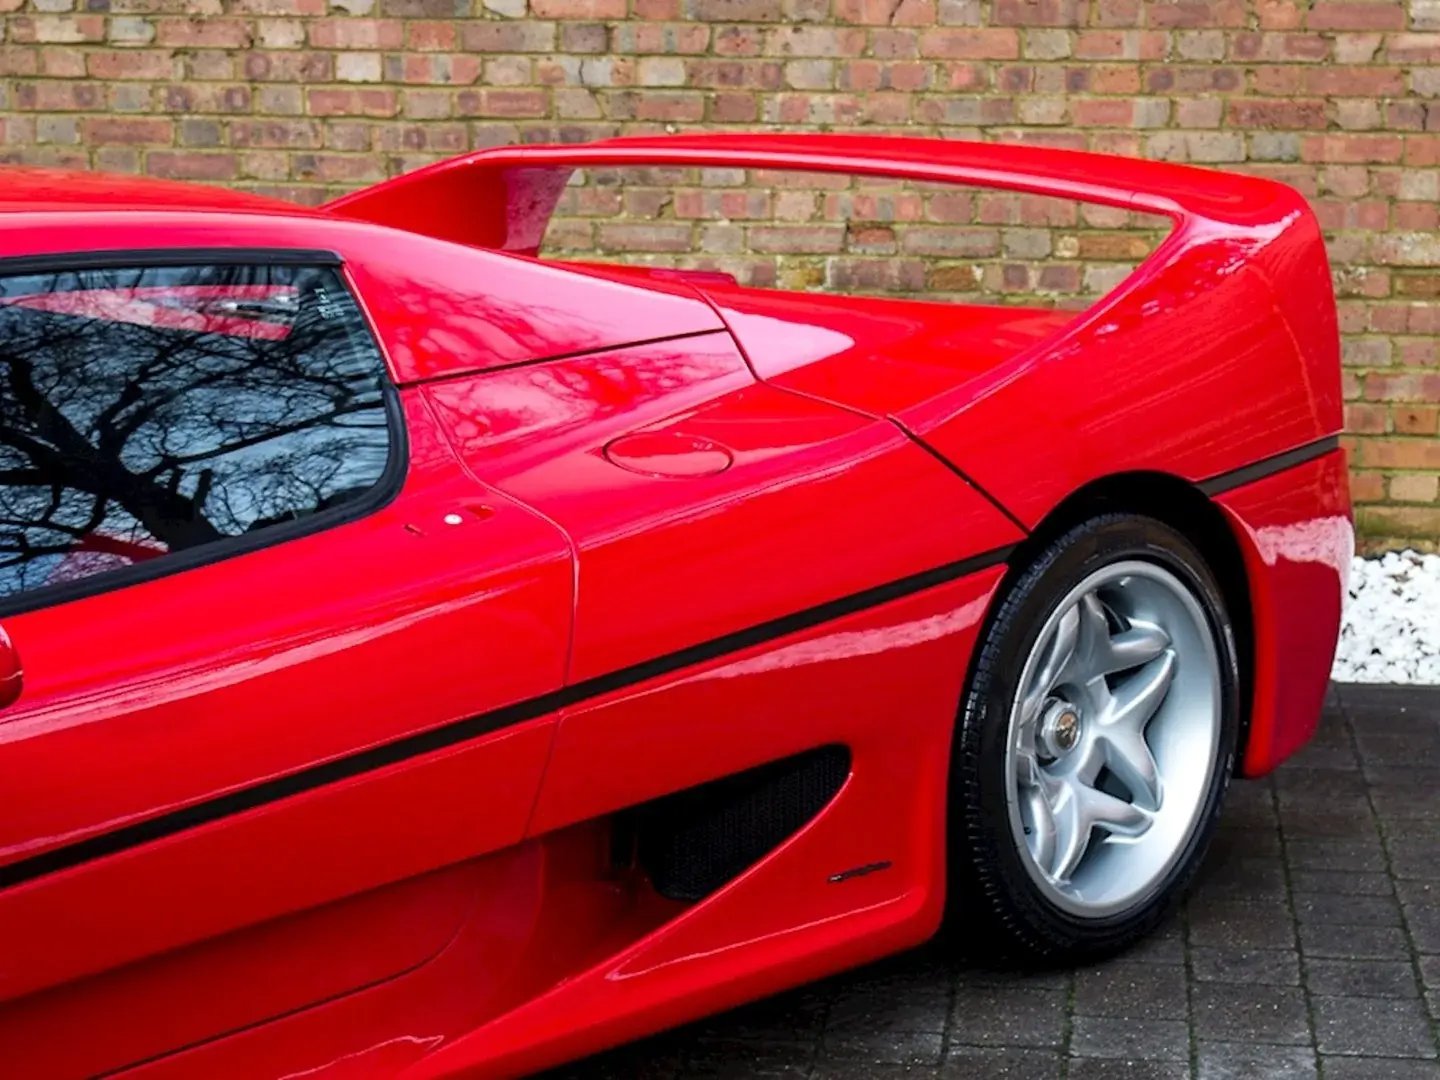 Ferrari F50
The F40 and F50 are the halo cars that raise the most questions, simply because of their age. Many mainstream lenders set an upper age limit on the cars they'll fund, which rules out a car from the late 1980s or 1990s before the conversation has even started. Specialist funders take a different view, looking at the car's condition, history and documentation, how it has been maintained and how it will be used, rather than the year on the logbook.
Structures on older cars tend to be simpler, often hire purchase over a shorter term, and the details a funder will want to see are the same ones a buyer would: service records, provenance and any Ferrari Classiche certification. We gather all of that early, so the finance is ready when the car is.
Ferrari Enzo and LaFerrari Finance
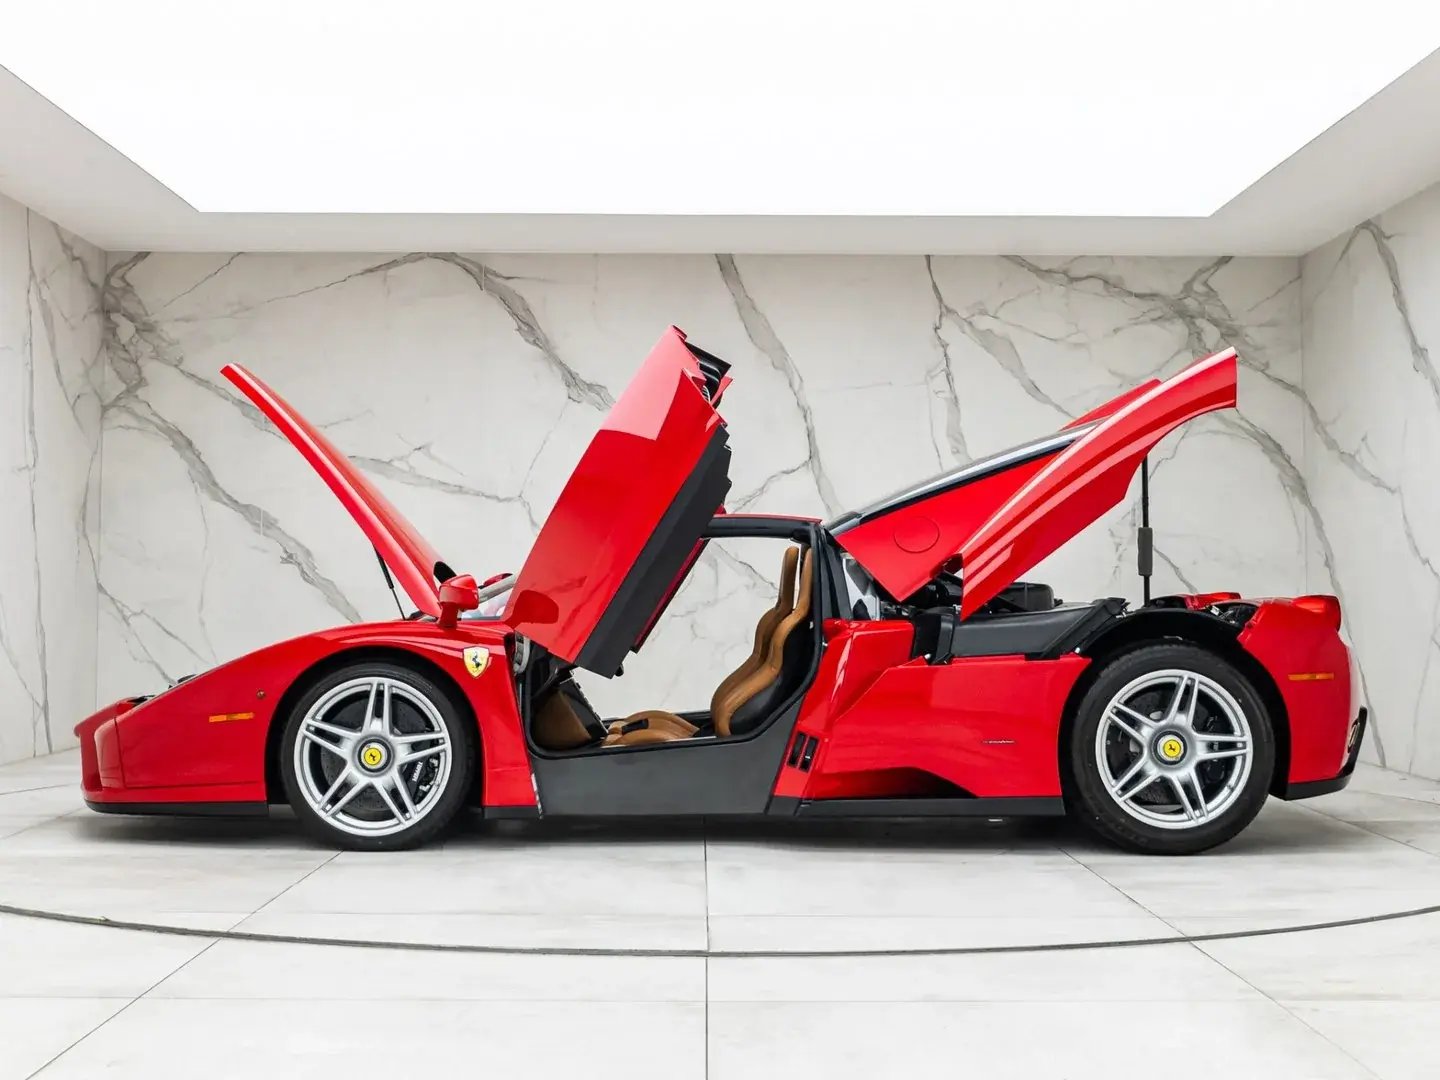 Ferrari Enzo
The Enzo and LaFerrari sit in the territory we work in most. For cars like these, Ferrari hire purchase with a Final Payment (Balloon) is the structure we arrange most often. The monthly payments cover part of the balance, the Final Payment (Balloon) sits at the end, and the car is yours once it's paid. How that final payment is set depends on the term, the expected mileage and the car itself, and on a low-mileage hypercar those details carry real weight. Lease Purchase works on a similar basis and can suit some business buyers. We walk through each structure in more detail in how supercar finance actually works.
Ferrari F80 Finance: Funding a New Allocation
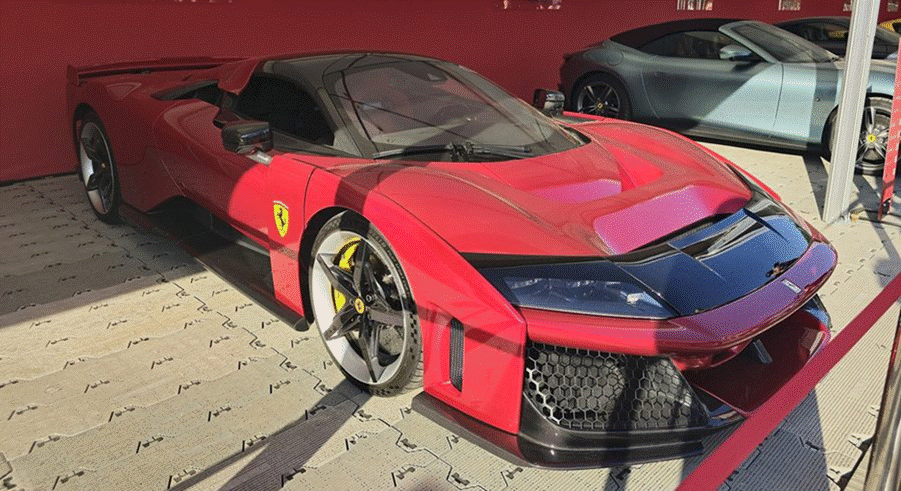
Ferrari F80. Image: Calreyn88, CC BY-SA 4.0, via Wikimedia Commons
The F80 is a different conversation again, because it's a brand-new car arriving through an allocation from Ferrari. Timing is everything. Clients often know when their car is coming months in advance, which gives us the chance to have the structure agreed and ready for delivery, rather than chasing it in the final weeks. Some clients fund the deposit from cash, others release equity from cars they already own, and some refinance after delivery once they know how they'll use the car. Planning it early keeps every option open.
What a Funder Will Want to Know About a Halo Ferrari
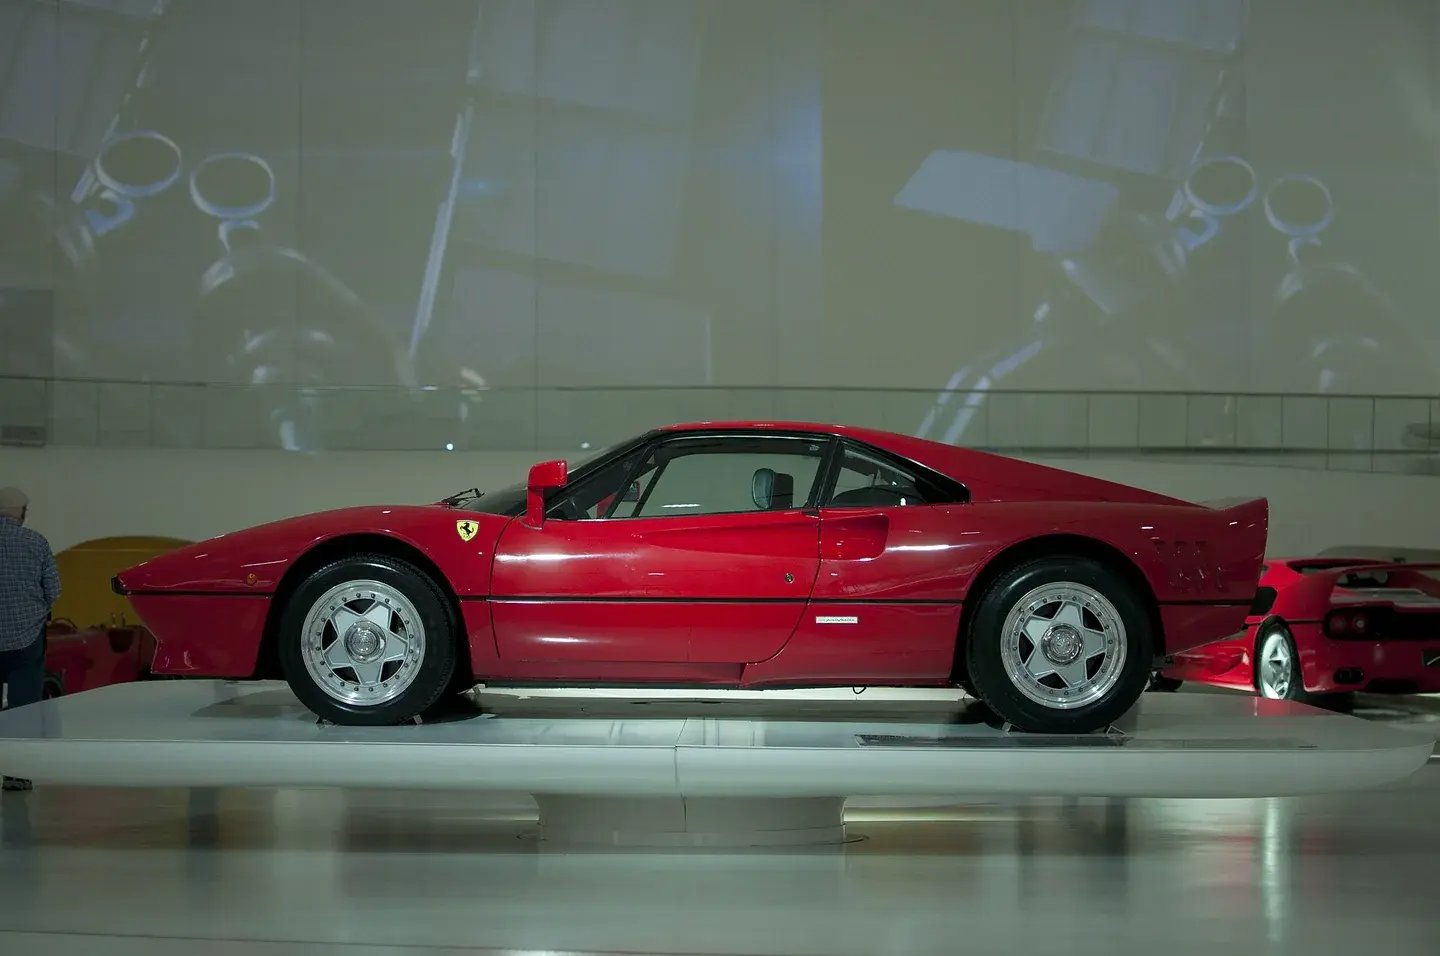
Ferrari 288 GTO. Image: Rahil Rupawala, CC BY 2.0, via Wikimedia Commons
Whichever halo car it is, the funder will want a clear picture of two things: the car and the way it will be owned. On the car side, that means its chassis and specification, its mileage, its service and ownership history, and for the older cars any Ferrari Classiche certification. These cars are rarely bought on a whim, and the paperwork that comes with them tends to be thorough, which helps.
On the ownership side, we'll ask whether you're buying personally or through a business, roughly how many miles a year the car will cover, how long you expect to keep it and whether the deposit is coming from cash or from equity released elsewhere. We bring all of that together into one clear case for the funder, so the decision is made on the car and on you, not on a box-ticking exercise. Funders will also want insurance arranged before the car is released, so it's worth having that conversation early too.
Releasing Equity From the Cars You Already Own
Anyone shopping for a halo Ferrari rarely owns just one car. If there's a car in the garage that's owned outright, equity release can unlock part of its value to fund the deposit on the next one, without selling it and without touching cash. If an existing agreement no longer suits, refinancing can bring it into line with everything else. It's the approach we took when a long-standing client released equity to acquire an F12tdf, and the one we followed when we funded a Ferrari 812 Competizione earlier this year.
Why Ferrari Finance at This Level Needs a Specialist
We're a broker, not a lender, and we work with a panel of specialist funders who understand cars at this level. On a halo Ferrari, that means placing the deal with a funder who knows the car, is comfortable with its age and value, and can move at the pace the purchase needs. It's why our Ferrari finance conversations start with the car, not a rate, and why we explain the difference in why a specialist car finance broker gets you a better deal than going direct.
It also means being straight with you when a car doesn't fit. Not every halo Ferrari will suit every funder, and when that's the case we'd rather say so at the start and look at the alternatives, whether that's a different structure, a different term or releasing equity elsewhere, than promise something that falls over late in the day.
Ferrari Halo Car Finance FAQs